
Fire damage claims in Ireland range from a contained kitchen fire to the total loss of a home. At every scale, understanding the claims process and documenting the damage properly affects how the claim is assessed.
Most Irish families assume documentation is straightforward and that the process will be simple. Knowing your policy terms and recording the damage properly are what allow a claim to be assessed correctly.
Fire Damage Claims Checklist – Immediate Action Steps
- Ensure Safety: Evacuate immediately, call 999/112
- Document Everything: Photograph all damage before cleanup
- Contact Insurer: Report the fire as soon as possible and get a claim number
- Secure Property: Board windows, cover holes, and prevent further damage
- Contact Loss Assessor: Get professional help before the adjuster visits
- Keep All Receipts: Document temporary accommodation and expenses
- Don’t Dispose of Items: Keep damaged goods until inspection is complete
- Get Multiple Quotes: Obtain contractor estimates for repairs
Government statistics show that chimney-related incidents account for 37% of residential fires across Ireland. Yet most homeowners have never dealt with insurance claims of this magnitude before.
This guide explains how fire damage claims work in Ireland: what a claim can include, how to document it, how to negotiate and how to avoid the common mistakes that weaken a claim.
At a Glance: What Each Level of Fire Damage Involves
| Fire Severity | Key Damage Components |
|---|---|
| Small Kitchen Fire | Smoke damage throughout the house, water damage, and professional cleaning |
| Single Room Fire | Structural repairs, smoke contamination in adjacent areas |
| Multiple Room Fire | Major reconstruction, extensive smoke damage |
| Partial House Fire | Significant rebuilding, extended temporary accommodation |
| Total Loss | Complete rebuild, full contents, months of alternative housing |
Most homeowners underestimate the full extent of fire damage costs. A kitchen fire that seems contained can still lead to a sizeable claim.
Why so much? The fire itself burns cabinets and appliances. But smoke spreads throughout your entire house. Water from fire hoses soaks into floors and walls. Professional cleaning becomes necessary in every room.
A fire confined to a single room usually means structural repairs as well. Smoke contamination affects adjacent areas. Hidden damage emerges during restoration.
How Underinsurance Reduces a Fire Claim
Underinsurance is one of the most common problems we come across in fire claims, and many homeowners have no idea it applies to them. It’s crucial to avoid costly underinsurance to protect your finances.
Here’s how it works. Your house cost €350,000 to build in 2018. Construction costs have increased 40% since then. Your actual rebuild cost is now €490,000. But your insurance coverage remains at €350,000.
You’re 29% underinsured.
Irish insurance policies contain “average clauses” that reduce every claim proportionally to underinsurance levels. A €100,000 kitchen fire becomes a €71,000 settlement. The €29,000 difference comes out of your own pocket.
Most homeowners only find this out after a fire, when it is too late to change their cover.
How to Check if You’re Underinsured
Contact a qualified building surveyor for a current rebuild cost assessment. Compare this figure to your insurance coverage amount. If there’s a gap, increase your coverage immediately.
Don’t rely solely on online calculators for rebuild cost estimates. Professional assessments cost €300-500 but provide accurate valuations that can help ensure adequate coverage and prevent underinsurance issues during claims.
Fire Damage Insurance Claim Process in Ireland
Understanding the real insurance claims process helps you participate effectively and avoid costly mistakes at each stage.
| Stage | Timeline | What Insurance Company Does | What You Should Do |
|---|---|---|---|
| Initial Response | Day 1-7 | Assign an adjuster, schedule an inspection | Document damage, secure property, contact loss assessor |
| Investigation | Week 2-4 | Inspect the property, investigate the cause | Provide documentation, cooperate fully, and gather evidence |
| Assessment | Week 4-8 | Value damage, apply policy terms | Submit receipts, get contractor estimates, query any valuation that leaves out part of the loss |
| Negotiation | Week 8-12 | Present settlement offer, negotiate terms | Review the offer, negotiate professionally, and take advice before accepting an offer |
| Settlement | Week 12+ | Finalise agreement, issue payment | Review documents carefully, sign the agreement, and receive payment |
The assessment process begins with fire cause determination. Insurance companies need to establish whether the fire resulted from covered circumstances or situations that might reduce coverage.
They examine maintenance records carefully. They check safety equipment functionality. They investigate the circumstances surrounding the fire’s start. Every detail matters for coverage decisions.
What Insurance Adjusters Really Look For
Various repair approaches may be suggested. Ensure all options are fully documented and explained.
They document damage extent using photos and measurements. But they also look for evidence of negligence or maintenance failures. They may also check whether smoke alarms were working. Poor electrical maintenance suggests negligence. Unmaintained chimneys indicate safety violations. These are some of the main reasons insurance claims get denied.
They calculate repair costs using industry databases and local contractor rates. Their estimate may be based on patch repairs where you believe full replacement is needed, or may not fully allow for specialist smoke and soot restoration. These are the points worth checking closely.
What Causes House Fires in Ireland
Understanding fire causes helps with prevention and supports your insurance claim because cause determination directly affects coverage decisions.
Irish fire brigades responded to nearly 20,000 fire incidents in 2024. Residential fires represent the largest category of emergency calls.
Chimney Fires – 37% of Home Fires
Chimney-related fires dominate residential fire statistics across Ireland. Creosote buildup creates highly flammable conditions that ignite during normal fireplace use.
Annual professional cleaning prevents most chimney fires. However, many homeowners skip this maintenance to save money. Insurance companies examine chimney maintenance records during claims investigations.
Without documented maintenance, coverage may be affected if negligence is determined to be a factor in the fire’s cause.
Cooking Accidents Create Complex Claims
Kitchen fires often lead to larger claims than people expect because damage extends far beyond the immediate fire area. Grease ignition spreads rapidly. Unattended food preparation creates dangerous conditions. Equipment malfunctions cause unexpected fires. Following our 25 tips for preventing kitchen fires can help mitigate these risks.
These fires create extensive smoke damage throughout entire houses, even when fire damage remains contained to kitchen areas. Professional cleaning becomes necessary in every room. Water damage from firefighting efforts affects flooring and walls.
Electrical Problems and Maintenance Records
Electrical fires result from ageing wiring systems, overloaded circuits, and appliance failures. Insurance companies examine electrical maintenance history very carefully during claims investigations.
Recent electrical inspections support your claim and demonstrate responsible homeownership. Outdated electrical certificates suggest maintenance negligence. Missing documentation raises coverage questions.
Have your electrical system inspected every five years by qualified electricians. Keep all certificates and maintenance records. You’ll need them if electrical problems cause fires.
Types of Home Insurance Coverage for Fire Damage
Most Irish home insurance policies cover fire damage, but understanding your home insurance policy helps you document the claim completely and present it under the right sections of your cover.
Structural Damage and Rebuilding Costs
Building insurance covers repairs or rebuilding for walls, ceilings, floors, roofing, and all permanent fixtures. This coverage extends beyond basic repairs to include professional restoration services needed to return your house to livable condition.
Professional restoration involves extensive cleaning, deodorisation, and specialised repairs that cost much more than standard construction work. Smoke damage remediation requires specialist equipment and techniques. Water damage restoration prevents long-term structural problems.
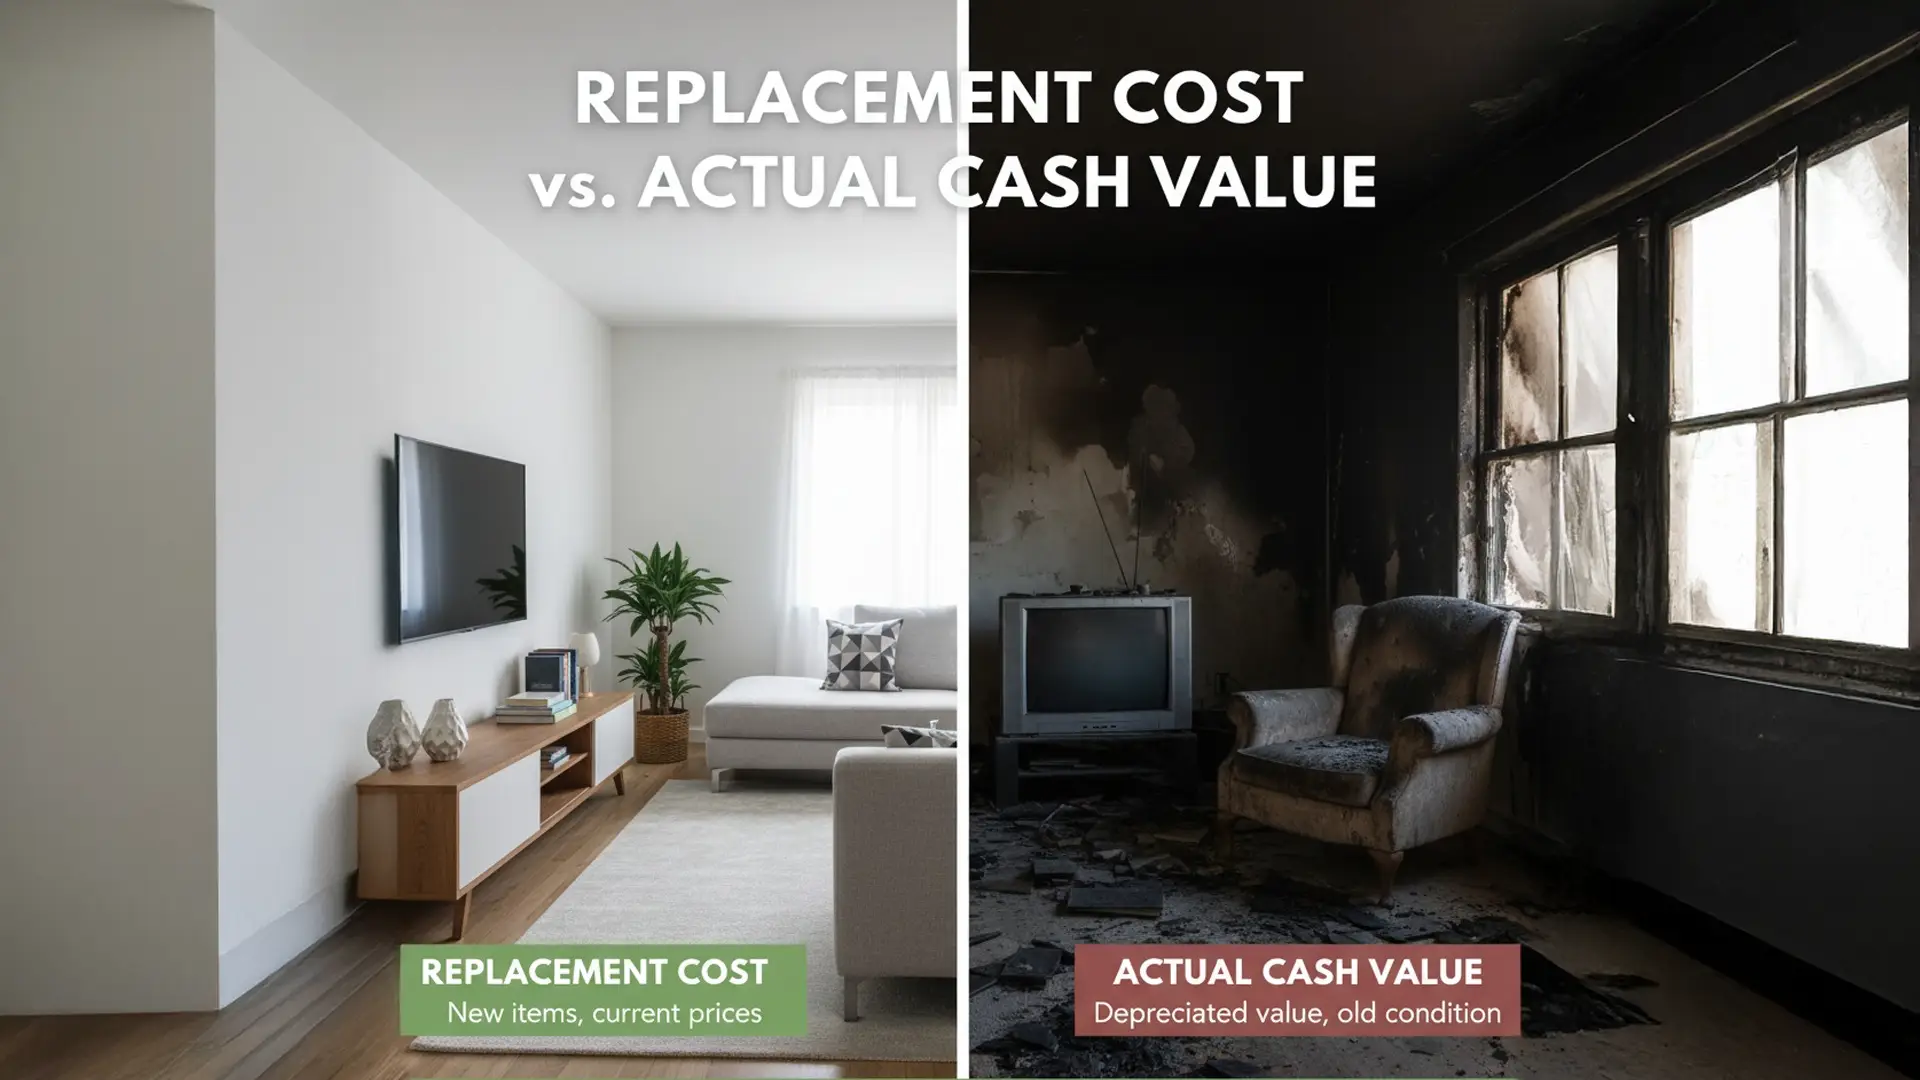
Contents Insurance: Replacement Cost vs Actual Cash Value
Contents coverage protects personal belongings damaged or destroyed by fire. The type of content coverage you have makes an enormous difference in settlement amounts.
Replacement cost coverage pays current prices for equivalent new items. A five-year-old television gets replaced with a current equivalent model at today’s retail prices.
Actual cash value coverage only pays depreciated amounts based on item age and condition. That same television might only receive 30% of its original purchase price.
Check your policy immediately. This distinction can make a large difference to how your contents are valued.
Alternative Accommodation During Repairs
Alternative living expenses become crucial when fire damage makes your house uninhabitable. This coverage typically includes hotel or rental costs, additional meal expenses, storage fees, and transportation costs.
These expenses accumulate quickly. €200-300 per day for families is common. Coverage continues for months during major repairs. Total alternative accommodation costs often exceed €30,000 for significant fire damage.
Alternative accommodation costs require careful documentation to support your claim. Keep all receipts for accommodation, meals, and transportation expenses. Ensure all costs are reasonable and necessary due to the fire damage.
Steps to Take After Fire Damage for Insurance Claims
Your actions in the first 72 hours after a fire matter both for your family’s safety and for how your claim is assessed. For a detailed guide, see our article on what to do after fire damage to your home.
Immediate Actions After Fire Damage (First 24 Hours)
1. Ensure Safety First: Evacuate everyone immediately. Don’t re-enter for any reason, even valuable possessions.
2. Call Emergency Services: 999/112 for fire, police, ambulance as needed. Wait for official clearance.
3. Document All Damage: Photograph fire, smoke, and water damage from multiple angles. Take hundreds of photos.
4. Contact Insurance Company: Report the fire as soon as possible, as your policy requires. Obtain a claim reference number. Answer the insurer’s questions fully and accurately.
5. Secure Property: Board windows, cover roof holes, lock entry points. Document security measures.
6. Contact Loss Assessor: Get professional representation before meeting the insurance adjuster.
Safety considerations must come first in every fire situation. Evacuate everyone immediately and don’t re-enter the building for any reason. Call 999 for emergency services and wait for official clearance before accessing your property.
Documentation should begin as soon as safely possible because preserved evidence is what supports every part of the claim. Photograph all damage from multiple angles. Include fire damage, water damage from firefighting efforts, and smoke contamination throughout the house.
Professional Help vs DIY Claims
A professional loss assessor specialises in representing homeowners during insurance claims. They understand documentation requirements, policy interpretation, and how to negotiate with insurers.
Early professional involvement can help you avoid costly mistakes. Learn more about how loss assessors can help.
DIY claims can be challenging because homeowners may lack technical knowledge about construction costs, policy terms, and negotiation strategies. Professional representation helps ensure all eligible damage is properly documented and presented.
Case Study: Dublin Kitchen Fire Claim
South Dublin Kitchen Fire – €85,000 Settlement
Initial Insurance Offer: €47,000
Final Settlement: €85,000
Difference from Initial Offer: €38,000 (81%)
The Situation: The A Family suffered kitchen fire caused by an electrical fault in the oven. Fire contained to the kitchen, but smoke damage spread throughout the three-bedroom semi-detached house.
Insurance Company’s Assessment: Adjuster valued the claim at €47,000, covering basic kitchen repairs. Smoke damage remediation and temporary accommodation costs were not fully included.
Professional Intervention: Loss assessor identified additional damage including extensive smoke contamination requiring professional cleaning in all rooms, water damage to flooring, hidden electrical damage requiring rewiring, and six months of increased living expenses.
Result: After negotiation, the claim settled at €85,000, which was €38,000 more than the initial offer.
Common Fire Damage Claim Mistakes to Avoid
Understanding common insurance claim questions and avoiding frequent mistakes keeps your claim on a sound footing.
Documentation Gaps That Weaken a Claim
Poor documentation causes more avoidable trouble than almost anything else. Insufficient photographs can’t prove damage extent. Incomplete inventories can’t support replacement costs. Missing receipts can’t establish ownership values. Use our ultimate insurance claim checklist to stay organised.
Understanding how to deal with insurance adjusters after a house fire begins with proper documentation. Clear, professional evidence makes each item easier to agree and leaves less room for dispute.
Premature Cleanup Destroys Evidence
Instincts encourage cleaning up and moving forward after fires. However, disposing of damaged items before professional evaluation can make it hard to prove what was lost. An item thrown out without a photograph or record is difficult to include in the claim.
Wait for official clearance from adjusters before discarding anything. Photograph items before disposal. Keep samples of damaged materials for evidence.
Accepting First Settlement Offers
A first offer is not always the final figure. Where an offer leaves out damage or costs your policy covers, those points can be raised with the loss adjuster and backed up with evidence.
Professional review identifies whether initial offers accurately reflect all losses and policy benefits.
Fire Safety and Insurance Compliance
Preventing a fire is far better than claiming for one. Proper safety compliance also protects your insurance coverage if fires occur despite your best efforts.
Smoke and Heat Alarms
Fit smoke alarms on every level of your home and a heat alarm in the kitchen, and test them regularly.
Some policies include conditions about smoke alarms and maintenance. Check your policy wording so you know what it requires. Document all testing and maintenance activities.
Maintenance That Supports Insurance Claims
Annual chimney cleaning prevents fires and creates documentation supporting insurance claims. Electrical system inspections identify hazards and demonstrate responsible homeownership. Boiler servicing ensures heating equipment operates safely.
Keep all maintenance certificates and service records. Insurance companies review these documents during claim investigations. Proper maintenance supports your coverage and prevents negligence arguments.
Frequently Asked Questions About Fire Damage Claims
How long do fire damage claims take to process in Ireland?
Simple fire damage claims typically take 6-12 weeks to process and settle. Complex claims involving significant damage can take 6-12 months. Total loss claims often take 12-18 months. Learn more about how long it takes to settle a claim.
Do I need receipts for everything damaged in the fire?
Receipts help establish value, but aren’t always required. Credit card statements, bank records, warranty documentation, and photographs can prove ownership. Maintaining a home inventory before incidents makes claims much smoother.
Will my home insurance premiums increase after a fire claim?
Many insurers review the premium at renewal after a fire claim, and the effect varies from one insurer and policy to the next. For a genuine fire loss, the cost of repairs is usually much greater than any change in premium, but check with your insurer or broker how a claim may affect your renewal.
Can I choose my own contractors for fire damage repairs?
Yes, you can select your own contractors. Insurance companies may have preferred networks, but you’re not required to use them. Obtain multiple estimates from reputable contractors who understand fire damage restoration requirements.
Can I reopen my fire damage claim for additional damage?
Most policies allow claims to be reopened for additional damage discovered within 12-24 months. Time limits vary by insurer and policy terms. Document newly discovered damage immediately and notify your insurer promptly.
Does smoke damage alone justify an insurance claim?
Yes, smoke damage alone can justify significant claims. Smoke contamination affects entire houses even when fire damage is contained to one room. Professional cleaning and restoration can cost tens of thousands of euros.
Emergency Contacts and Resources
Emergency Services
Fire, Police, Ambulance: 999 or 112
ESB Emergency: 1850 372 999
Gas Networks Ireland Emergency: 1850 20 50 50
Insurance and Consumer Resources
Competition and Consumer Protection Commission: www.ccpc.ie
Central Bank of Ireland: www.centralbank.ie
Fire Safety Information: www.fireireland.ie
Get Professional Fire Damage Claims Help
Fire damage claims involve substantial financial stakes and complex technical requirements. Professional assistance becomes valuable for most homeowners facing these situations.
Client Success Story
“Trevor was extremely professional and secured a settlement that far surpassed our expectations. The stress was taken off our shoulders completely.” – Lydia M., Dublin
5-star Google Review | Read more client reviews
Insurance Claim Solutions brings over 40 years of combined experience handling fire damage claims across Ireland. Our team includes qualified building surveyors and registered public loss assessors who understand both technical fire damage assessment and insurance industry procedures.
We manage the full claim for you, including detailed damage documentation, policy analysis and interpretation, settlement negotiation, and ongoing communication with insurance companies throughout the process.
In practice, that means we record every type of damage, check each part of your policy that may apply, set out the evidence clearly and negotiate with the insurer and its loss adjuster on your behalf.
This article provides general guidance about fire damage claims in Ireland based on our professional experience. For advice specific to your situation, contact our qualified loss assessors for a free consultation.