 Acts for the insurer
The Insurer’s Loss Adjuster
- Appointed by the insurance company
- Assesses the claim for the insurer
- Reports back to the insurer
Insurance Claim Help Ireland
Cracks that keep widening, doors and windows that start to stick, a floor that has dropped: these can be signs of subsidence, heave or landslip. Here we explain the difference between them, how home insurance usually deals with ground movement, and how Insurance Claim Solutions handles a subsidence claim with your insurer.
Call 01 870 9210Types of Ground Movement
Subsidence is the sinking of the ground beneath a building. It often shows up as cracking in walls, doors and windows that stick, or floors that are no longer level. Heave and landslip are two other forms of ground movement that can affect your property. Heave occurs when the ground beneath expands, pushing the foundation upwards, often due to the soil beneath rehydrating after a period of dryness. Landslip, on the other hand, involves the downslope movement of soil and rock, potentially destabilising the foundation.
The type of ground movement affects both the repair and whether your home insurance covers it.
Here's how different types of ground movement manifest:
Each type of ground movement needs a different repair. For example, heave might call for managing soil moisture, while landslip may need retaining walls. Identifying the cause correctly matters for the repair and for the insurance claim.
Get Free Claim Advice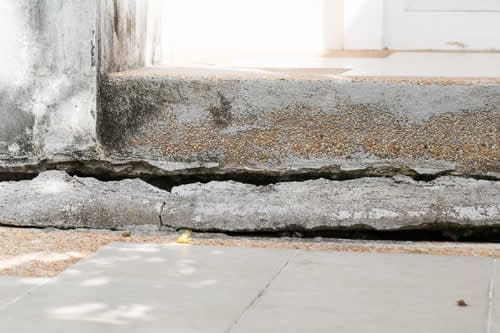
Home Insurance and Subsidence
Many home insurance policies cover subsidence, heave and landslip, but the details vary from policy to policy. Buildings insurance typically covers damage to the structure of your home, including the foundation and walls and floors, while contents insurance covers your possessions inside. Some policies may have exclusions or limitations, such as an initial excess for subsidence claims.
Check the subsidence section of your policy, including the excess, before you make a claim.
If you suspect subsidence, the first step is to contact your insurer immediately. They will usually appoint a loss adjuster, and often a structural engineer, to establish the cause and extent of the damage. Gather all relevant information, including photos of the cracks in the walls and any documentation related to previous repairs. Subsidence claims often involve further investigation and a period of monitoring before repairs are agreed, so it helps to have someone keeping you informed. Do not carry out repairs, or cut back or remove trees near the property, until you have notified your insurer and it has had the chance to inspect.
Insurance Claim Solutions can manage the claim with your insurer, working alongside the engineers who establish the cause of the damage.
Get Free Claim Advice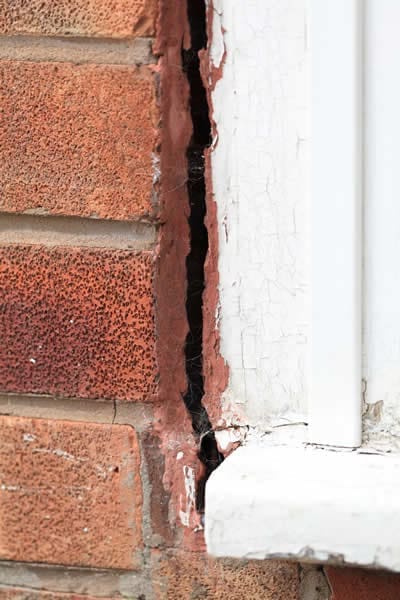
Loss adjuster or loss assessor?
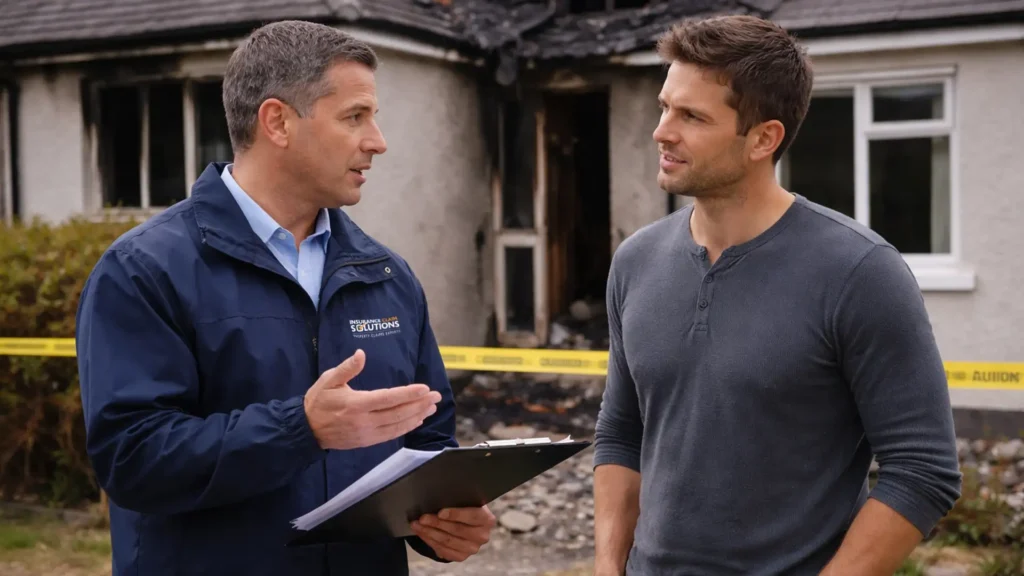
When you make a subsidence claim, your insurer sends a loss adjuster. They are appointed and paid by the insurance company, and they assess the claim on its behalf. A loss assessor does the same job from your side of the table: we are appointed by you, and we work for you.
Acts for the insurer
 Acts for you
Insurance Claim Solutions acts for you, the policyholder, from the first inspection to settlement.
Managing Subsidence Issues
Addressing subsidence requires tailored solutions depending on the cause and severity. Underpinning is a common method to fix subsidence, involving strengthening the foundations to prevent further movement of the ground beneath. Other options include resin injections to stabilise the soil beneath and drain repairs to address issues that cause subsidence.
Tell your insurer and let it inspect before deciding on a repair, and take advice from a qualified surveyor or structural engineer, especially where the damage is severe.
Some everyday measures can help reduce the risk of subsidence. Regularly inspect your property for cracks in the walls and other signs of subsidence. If you notice any, tell your insurer and take advice from a qualified surveyor or engineer before any repairs are carried out. Ensure drains are well-maintained to prevent leaks that wash away the soil beneath the foundation. Trees close to a building can draw moisture from the soil. Do not remove or cut back large trees near your home without advice from a qualified surveyor or engineer, as removing them can cause the ground to heave. If you have already noticed signs of movement, tell your insurer first.
These steps may help, but they do not remove the risk of ground movement.
Insurance Claim Solutions handles subsidence claims for homeowners and businesses. We record the cracking and movement, check the damage against your policy and deal with your insurer, its loss adjuster and the engineers on your behalf. We keep you informed through the investigation and monitoring stages.
Get Free Claim Advice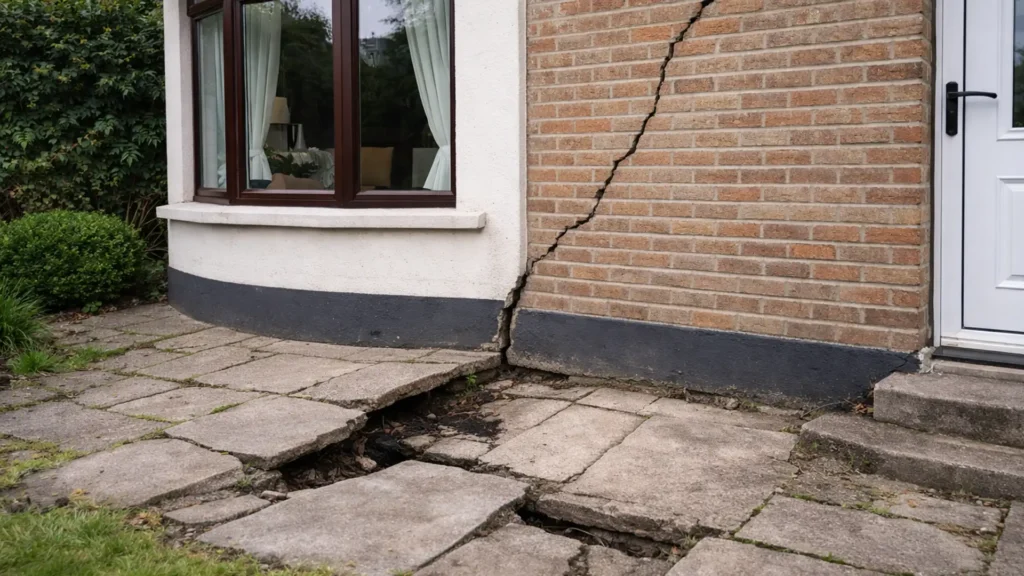
Conclusion
Home insurance cannot stop ground movement, but it may pay for the damage it causes. Check whether your policy covers subsidence, heave and landslip, and note any exclusions, limits or special excess.
Prompt attention to any signs of subsidence, including telling your insurer, can help limit further damage. Keep a record of any cracks you notice, with dates and photographs, as this helps when the insurer investigates.
Subsidence, heave and landslip can cause serious structural damage, and these claims can take a while to investigate. If you see signs of ground movement, tell your insurer and keep a note of what you have seen and when. Insurance Claim Solutions can then assess the damage, take over the claim and deal with the insurer on your behalf through to settlement.
Get Free Claim Advice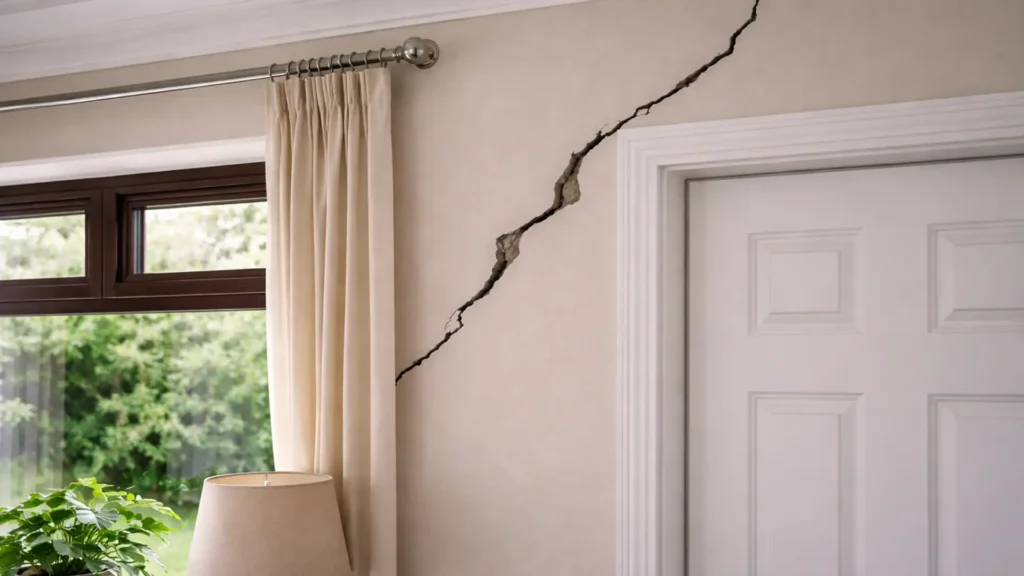
What happens next
A short conversation about the damage and your insurance cover. It’s free, and there’s no obligation.
A qualified loss assessor inspects the property, records the damage and identifies what should form part of the claim.
Documentation, valuations, insurer communication and negotiations are handled for you. You’re kept informed at every stage.
We deal with your insurer on the settlement under the terms of your policy. The insurer pays you directly.
Step 01 is a free, no-obligation conversation.
Public loss assessors
We deal with your insurer for you.
We keep you informed at every stage.
Talk to a loss assessor. The initial consultation is free, with no obligation.
24/7 helpline 01 870 9210