After a fire, flood or break-in, the shock is soon followed by the insurance claim itself: forms to fill in, policy wording to work through, and meetings with your insurer’s appointed loss adjuster. Most people have never made a large claim before and aren’t sure where to start. You don’t have to do it alone.
A loss assessor is a professional advocate who works exclusively for you, the claimant. They are not the same as the adjuster sent by your insurer. Their job is to manage your claim from start to finish and put your side of it to the insurer. The most common question policyholders ask is, “How much does this help cost?” Understanding the loss assessor fees helps you decide whether appointing one is right for your claim.
What Does a Loss Assessor Typically Cost?
So, how much does a loss assessor really cost you? In Ireland, loss assessors generally work on a percentage-based fee, typically ranging from 5% to 10% of the final insurance settlement negotiated on your behalf. This fee will also have VAT added, so be sure to clarify this from the outset.
Many loss assessors work on a ‘No Win, No Fee’ basis. For you as the policyholder, this means that if no settlement is agreed, no fee is payable. The fee is not an upfront cost; it is taken from the settlement when your claim is paid. Before you appoint any loss assessor, ask them to confirm their fee, and whether VAT is added, in writing.
What a Loss Assessor Does for You
Hiring an experienced loss assessor means you have a professional on your side of the claim. The loss adjuster works for the insurance company; your loss assessor works for you. When you appoint an assessor, you are engaging a specialist who knows how a home insurance claim is assessed and settled.
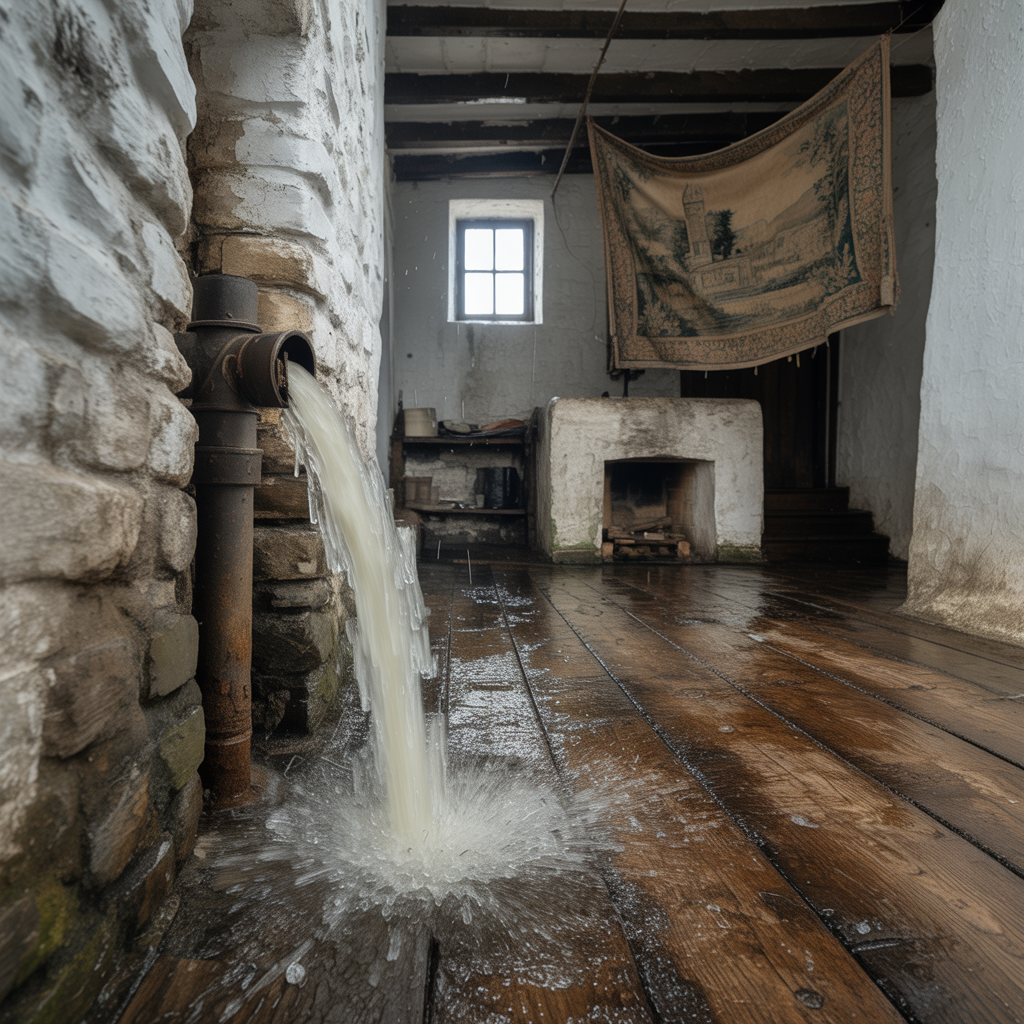
Their value goes far beyond simply filling out forms. They conduct a thorough assessment of your property damage, including hidden damage that is easy to overlook, such as after a burst pipe insurance claim or long-term structural issues after a flood. They record every item of loss and know how to cost repairs and replacements at current market rates. Because they know how insurers and loss adjusters assess a claim, they can present your case clearly, handle all communications, and manage the entire claim handling process, which can help to speed up your insurance claim. That takes the day-to-day work of dealing with insurers off your hands, so you can concentrate on your home, your family or your business.
The Critical Difference: Understanding Loss Assessor vs. Loss Adjuster
The two titles sound alike, but the roles are quite different. One is appointed by the insurer; the other is appointed by you.
A Loss Assessor, often called a Public Loss Assessor, is an independent professional hired by you. They represent you throughout the claim, preparing and presenting it to the insurer under the terms of your policy.
A Loss Adjuster, on the other hand, is appointed and paid by the insurance company. While they are bound by professional ethics, their primary role is to investigate the claim for their employer. They represent the insurance company’s interests by assessing the validity and value of the claim from the insurer’s perspective. Put simply, the loss adjuster assesses the claim for the insurer, while a loss assessor prepares and presents it for you.
How are Loss Assessor Fees Paid?
This leads directly to another common query: who pays for a loss assessor? You, the policyholder, are responsible for the loss assessor fees. However, this payment is not typically an out-of-pocket expense. The standard practice is for the fee to be deducted directly from the settlement cheque issued by the insurer.
Here is how that works in practice. For example, if your claim amount for major water damage is settled at €50,000, a 10% fee (€5,000 + VAT) would be deducted from that settlement before the balance is paid to you. You do not pay the fee separately or in advance.
When Should You Appoint a Loss Assessor?
A loss assessor can help with any property claim, but some situations call for one more than others. If you find yourself asking “do I need a loss assessor?” it is worth talking to one when you are facing complex claims or a large loss. This includes major events like a house fire with resulting smoke damage, widespread flooding, or severe storm damage.
If you feel overwhelmed by the complexity of the claim process or simply don’t have the time or expertise to manage it, an assessor can take that work off your hands. It is also worth getting advice if you are unsure about a settlement offer or if the insurer is disputing parts of your claim, such as in cases involving malicious damage to property. Getting an assessor involved early means the damage is recorded properly before repairs start, and the claim is managed from day one.
Talk to Insurance Claim Solutions
Insurance Claim Solutions is regulated by the Central Bank of Ireland (Reg. No. C423441). As a public loss assessor, we act for you, the policyholder, and deal with your insurer and its loss adjuster on your behalf. If you would like to talk about your claim, contact us.