By Trevor Kelly MSCSI, Public Loss Assessor, Insurance Claim Solutions
Making a home insurance claim is one of those things you hope never to need. When the moment arrives, though, most homeowners find they’re dealing with a process they’ve never gone through before, at exactly the point when they have the least mental bandwidth to figure it out.
This guide walks you through the full claims process in plain English, from the first phone call to final settlement. It also covers what you can do if you disagree with the insurer’s assessment.
Table of Contents
How to Make a Home Insurance Claim in Ireland
The basic process follows these steps:
| Make your property safe and prevent further damage where possible | Document everything before any clean-up or repairs begin: photographs, video and written notes | Report the incident to your insurer as soon as possible (most policies require prompt notification) |
| Have your policy number and a description of the loss or damage ready when you call | Receive a claim reference number and confirmation of next steps | A loss adjuster is appointed by your insurer to inspect the damage |
| The loss adjuster visits your property and submits their report | Your insurer makes a settlement offer based on that report | You accept the offer, negotiate it, or dispute it |
That last step is where most guides stop. It’s also where the process gets complicated.
A note on timing: if the damage is severe and your home is unsafe or uninhabitable, most insurers have an emergency line available outside office hours. This number is usually on your policy documents. Use it; emergency callout cover can prevent further damage and protect your position in the subsequent claim.
What Your Home Insurance Policy Actually Covers
Before you make a claim, it helps to understand what your home insurance policy is designed to cover and where the gaps are.
Standard home insurance covers two things: the structure of your property (buildings cover) and its contents. Most policies also include legal liability cover, which protects you if a visitor to your property is injured or if you accidentally cause damage to a neighbour’s property.
Buildings cover typically includes damage caused by the following:
- Fire and smoke
- Storm and wind damage, including damage to your roof, chimney, gutters, and windows and doors
- Flood and water damage from burst pipes, plumbing failures, or surface water
- Theft and break-in, including structural damage caused during a burglary
- Subsidence (subject to specific policy conditions)
- Impact damage from falling trees, debris, or vehicles
- Oil leaks from heating systems
Contents cover typically includes furniture, carpets, valuable items, and personal possessions inside the home. Some policies extend to an outhouse or external storage.
What most policies exclude is equally important to understand. Wear and tear is a standard exclusion. If your roof needs replacing because it has aged, that is a maintenance issue, not an insurable event. The same applies to gradual deterioration of plumbing or guttering. Damage must result from a sudden, unforeseen event, not from deferred upkeep.
One thing worth checking before any claim: your policy excess. This is the out-of-pocket amount you contribute before the insurer pays. On a small claim, the excess can sometimes approach the full cost of repair, making it questionable whether claiming is the right decision at all.
What Documentation You’ll Need
Before the loss adjuster appointment, gather everything you can.
Start with your policy schedule, which sets out your cover limits, excess levels, and any special conditions. Have this to hand before you call.
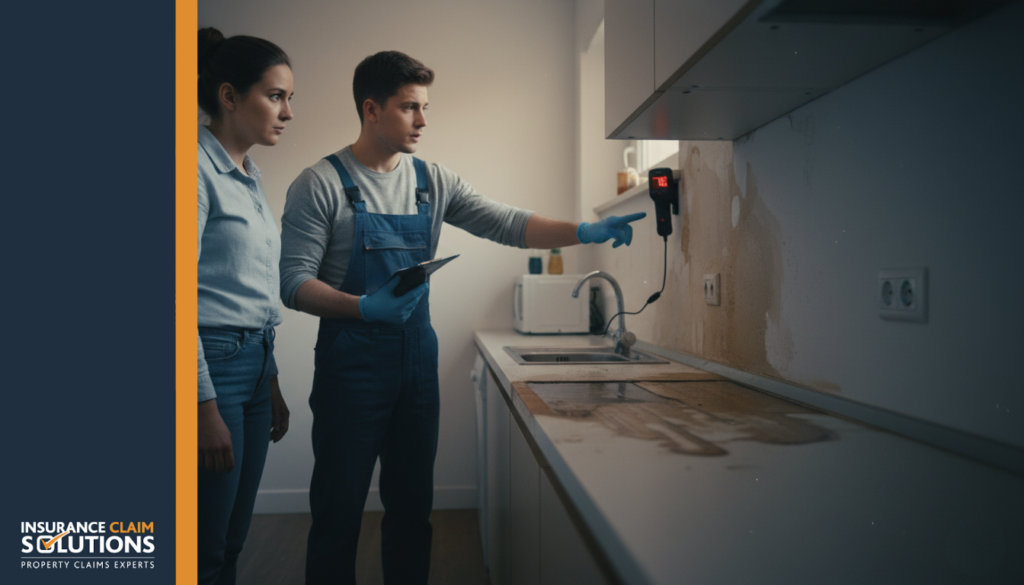
For the damage itself, document thoroughly before anything is touched:
| Photographs and video of all damage, including areas that may need to be cleaned or made safe beforehand | Receipts or proof of purchase for damaged items – if you no longer have receipts, bank statements or credit card records often serve as evidence |
| A written account of when the incident occurred, what you observed, and what steps you took immediately | If there was a theft or break-in, the Garda reference number from when you reported the loss |
Keep receipts for any emergency spend to protect the property, such as boarding up windows, arranging temporary repairs to stop water ingress, and moving damaged items to a safe place. These costs are often recoverable, but only with documentation.
Keep damaged items until your insurer or its loss adjuster has had the chance to see them, unless leaving them in place creates a safety or health risk.
Take reasonable steps to prevent further damage and keep receipts, but check with your insurer before starting permanent repairs. Once items have been fixed or removed from your home, evidence disappears and scope disputes become harder to resolve.
The Loss Adjuster Visit: What’s Actually Happening
This part of a home insurance claim is often unfamiliar to homeowners.
When an insurer appoints a loss adjuster, they are appointing someone to assess the claim on their behalf. Loss adjusters are professionals. Their report forms the basis of your offer, and their instructions come from the insurance company, not from you.
Their job is not to build your claim for you. They are there to assess it accurately, within the terms of your policy, on their client’s behalf.
That distinction becomes important the moment any element of your claim is borderline: the extent of the damage, whether a particular item is covered, or whether the cause triggers your policy. At those decision points, the loss adjuster’s report forms the basis of the insurer’s offer, so check it against your own records and ask the insurer to explain how the figure was calculated before you accept.
How Long Does a Claim Take in Ireland?
Timescales vary widely, because they depend on the complexity of the damage, how promptly it is handled, and whether anything is disputed.
Simple claims, such as a burst pipe causing water damage to a carpet, with clear liability and a modest repair cost, can be dealt with more quickly. Claims involving structural damage, significant roof repairs, or any dispute over coverage or valuation can take considerably longer.
If your home is uninhabitable during the process, your policy may cover alternative accommodation costs. Refer to your policy schedule for the limit and duration.
A dispute about scope or value is a common cause of delay, and resolving it properly takes evidence and time.
Why Some Home Insurance Claims Fall Short
Where a homeowner is unhappy with a settlement, a common reason is that part of the damage was not recorded or a point of policy wording was not raised. Checking the offer against your own records before you accept is sensible.
Underinsurance is one possible cause. If your building’s sum insured does not reflect the actual rebuild cost of your home at the time of the claim, your insurer can apply what’s known as the average condition. This means your payout is reduced in proportion to the degree of under-insurance. A home insured for €200,000 with a true rebuild cost of €300,000 may only receive two-thirds of any valid claim, regardless of the damage amount. Rebuild costs can change over time, so it is worth reviewing your sum insured regularly.
Scope disputes are also common, particularly after fire, flood, or water damage. The visible damage may be obvious. Hidden damage to the subfloor, attic insulation, electrics, or structural elements behind walls may not appear in the initial assessment, so it is worth recording it and raising it with the insurer.
Policy interpretation also matters. Whether smoke damage from a fire is covered under the same event as the structural damage, how your policy handles subsidence, or what counts as “accidental” versus resulting from wear and tear, these distinctions affect the final figure.
Betterment deductions are a related point of dispute. Insurers can argue that part of the repair cost reflects a pre-existing condition rather than the insurable event. This is a recognised principle, and your policy wording sets out how it applies.
Once you have accepted a settlement, your options for reopening it may be limited, so check the offer carefully before you agree.
Will a Claim Affect My Premium?
Making a claim may affect your renewal premium. The extent depends on your insurer, the nature of the claim, and your claims history. Some insurers increase the premium or apply a higher excess; others may not.
This is a legitimate concern, but it should not prevent you from making a valid claim. If you have suffered a significant loss, the purpose of home insurance is to cover it. Whether to claim on a smaller loss is a decision for you, taking your excess into account.
If you are unsure whether a borderline claim is worth pursuing, you can ask us for a view. Your policy will still require you to notify your insurer promptly, so do not delay reporting the damage.
When to Get a Loss Assessor
A loss assessor can be appointed before the loss adjuster visits or after the insurer has made an offer.
A public loss assessor manages your insurance claim on your behalf. They act for you, not the insurer.
You can appoint a loss assessor to act for you. They handle the documentation, the damage assessment, the discussions with the insurer and all communication with the insurance company, so that the damage is recorded and put to your insurer.
It makes sense to consider a loss assessor when:
| The damage is significant: structural damage, fire, flood, extensive water damage, significant ground movement, or major roof failure | You are unsure whether the scope assessed by the loss adjuster matches what you are actually looking at | Your claim has been delayed, disputed, or rejected | You do not have the time or technical knowledge to manage the claims process yourself | You want someone acting for you rather than for the insurance company |
ICS works on a no win no fee basis, and the initial consultation is free.
A loss assessor can be appointed at any stage, but the earlier the better, while the scope and documentation of the claim are still being established. Always notify your insurer promptly; you can contact us at the same time.
How ICS Handles Home Insurance Claims
If you are dealing with property damage right now, you are likely trying to figure out what your policy actually covers and what the process ahead will involve. That is exactly what ICS is set up for.
Trevor Kelly has been managing home insurance claims across Ireland since 2009. He is a Chartered Building Surveyor (MSCSI, MRICS) and a public loss assessor. As a Chartered Building Surveyor and a public loss assessor, Trevor assesses both the physical condition of a property and the insurance process itself, and records the damage after a fire, flood or structural event, including elements that are not always immediately visible.
Here’s how it works. You contact ICS, describe the damage, and arrange a free initial consultation. The process is straightforward from there. Trevor will assess the damage, review your home insurance policy, and give you an honest view of your position before any fee arrangement is in place. If ICS takes on your claim, a surveyor and loss assessor manages everything from lodging the claim and liaising with the appointed loss adjuster through to final settlement.
Our fee terms are explained to you at the initial consultation.
Since 2009, ICS has handled more than 10,000 claims across Ireland, covering fire, flood, water damage, storms, subsidence, burglary, oil leak, and impact damage.

If you want a clear, independent view of your claim and where it stands, call 01 870 9210 or use the contact form on this page. The initial consultation costs nothing, and there is no obligation.
FAQ
Do I need a loss assessor for a home insurance claim?
You are not required to use one, but you have the right to appoint one. If your claim is simple and modest in value and you are satisfied with the offer, a loss assessor may not be necessary. If the damage is significant, the claim is disputed, or you have any doubt about whether the settlement reflects your actual loss, independent representation may be worth considering. ICS works on a no win no fee basis and the initial consultation is free.
What is the difference between a loss assessor and a loss adjuster?
A loss adjuster is appointed by your insurer to assess your claim on their behalf. A loss assessor is appointed by you to manage your claim on your behalf. The difference is whose interests each one represents.
Can I dispute a home insurance claim decision?
Yes. If you disagree with the offer or a decision to reject your claim, you can negotiate directly, escalate through the insurer’s internal complaints process, or refer the matter to the Financial Services and Pensions Ombudsman (FSPO) once you have received the insurer’s final response; time limits apply. A loss assessor can help you with a dispute about the claim.
What if my claim has already been settled?
If you have concerns about a claim that has already been settled, it may be worth seeking a professional view. The options available depend on the specific circumstances, including how the amount was agreed upon and whether the claim has been formally closed. Contact ICS for an initial discussion.
Does making a claim affect my no-claims bonus?
It often does. The specific impact depends on your insurer and your policy terms. Check your policy schedule or ask your broker before deciding whether to proceed with a borderline claim.
What is underinsurance, and how does it affect my claim?
Underinsurance means your buildings or contents sum insured is lower than the actual rebuild or replacement value. If the average condition in your policy is triggered, your payout is reduced proportionately, often significantly.
What should I do immediately after discovering damage to my home?
Make the property safe first. If there is an active water leak, isolate the supply. If there is fire or structural risk, leave the building and call the emergency services. Once the immediate risk is addressed, document everything before clean-up begins, and report the loss as soon as possible. Check with your insurer before starting permanent repairs; otherwise, the cost may be disputed.
Trevor Kelly Insurance Claim Solutions Limited, trading as Insurance Claim Solutions, is regulated by the Central Bank of Ireland (Reg. No. C423441). Trevor Kelly MSCSI is a member of the Society of Chartered Surveyors Ireland.