 Acts for the insurer
The Insurer’s Loss Adjuster
- Appointed by the insurance company
- Assesses the claim for the insurer
- Reports back to the insurer
Insurance Claim Help Ireland
Business interruption claims can be complex, particularly when loss of income, ongoing costs, and policy wording must all be carefully assessed. Insurance Claim Solutions helps businesses in Dublin and across Ireland document their lost income and extra costs, and present the business interruption claim to their insurer.
Call 01 870 9210Insurance Assessor
Business Interruption Insurance is designed to cover the loss of income that follows damage to your property from an insured event such as fire, storm, flood, burst water pipe, theft or malicious damage.
Loss of revenue resulting from property damage e.g. burnt down or flooded premises can exceed the value of the damaged property, so it needs to be assessed carefully and claimed as soon as possible.
Unfortunately Business Interruption policy cover does not apply automatically.
It is usually an extension to your property insurance policy and it can have several components such as profits, fixed costs, extra expenses etc. You need to make sure that your specific peril cover has business interruption extension. Your policy schedule will show whether it is included.
Get Free Claim Advice
Business Interruption Claim Support
As Business Interruption Claims are rarely straightforward, it helps to have a loss assessor involved rather than preparing the claim on your own.
Tell your insurer promptly, as your policy requires, and call us at the same time. The first weeks after the damage matter for recording the loss and planning how the business will keep trading.
Policy wording is often open to interpretation and if you are not an insurance expert, you may miss something in the small print.
Although your accountant may be able to come up with projected sales and profit figures, working out what can be claimed under your business interruption cover takes a detailed reading of the policy, the indemnity period and your trading figures.
If you need help with assessing your loss, interpreting your policy wording, or completing your Business Interruption claim, contact us.
We handle many different types of business claims, from fire damage to floods, water damage, subsidence, burglary and malicious damage.
We work alongside your accountant, using your trading records to show what the business would have earned had the damage not happened.
Get Free Claim Advice
Loss adjuster or loss assessor?
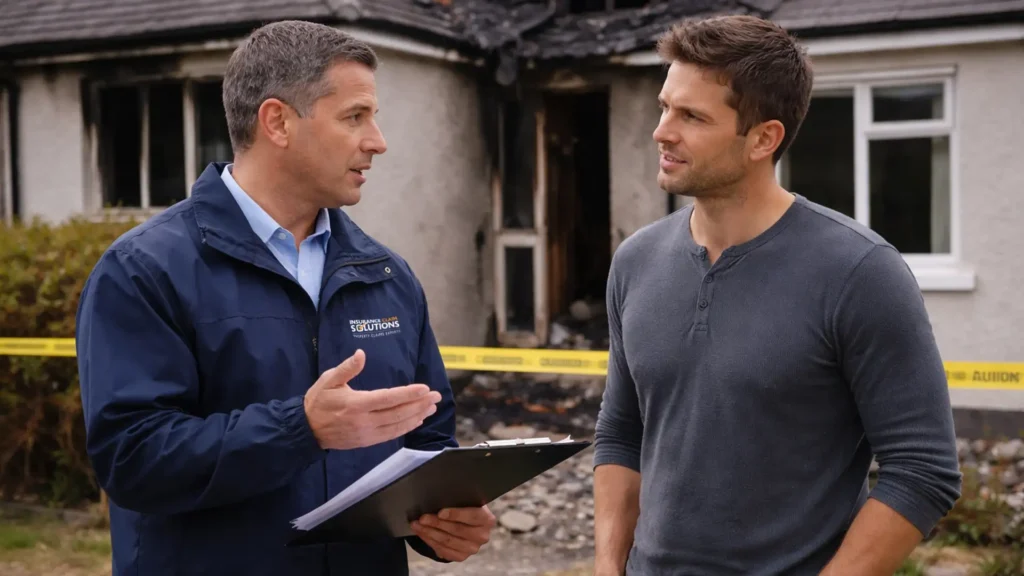
When you make a business interruption claim, your insurer sends a loss adjuster. They are appointed and paid by the insurance company, and they assess the claim on its behalf. A loss assessor does the same job from your side of the table: we are appointed by you, and we work for you.
Acts for the insurer
 Acts for you
Insurance Claim Solutions acts for you, the policyholder, from the first inspection to settlement.
Insurance Cover and the Indemnity Period
The indemnity period is a key part of business interruption insurance policies. It represents the timeframe during which the business interruption insurance covers lost profits and additional expenses following a covered peril.
The period starts from the date of the incident and runs for a set length of time, such as 12, 18, or 24 months. Losses after the period ends are not covered, so we check it early and plan the claim around it.
Get Free Claim Advice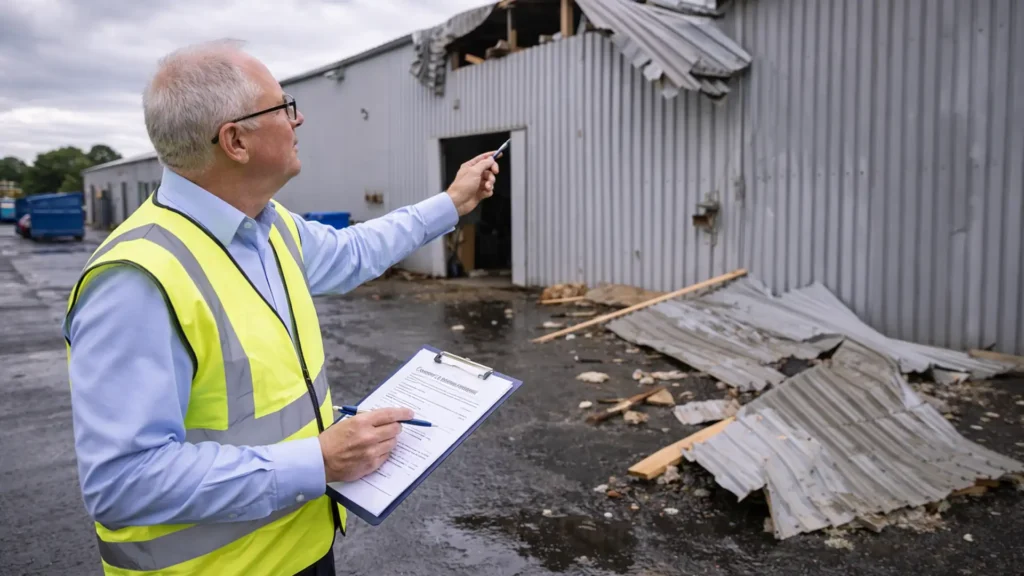
Evidence for Your Claim
A business interruption claim is built on figures, so the records you keep matter. Insurers may ask for management accounts, sales records from before and after the damage, payroll records and invoices for any extra costs, such as temporary premises or overtime. We gather these with you and your accountant, set out the loss in line with your policy wording and deal with the insurer and its loss adjuster until the claim is settled.
Get Free Claim Advice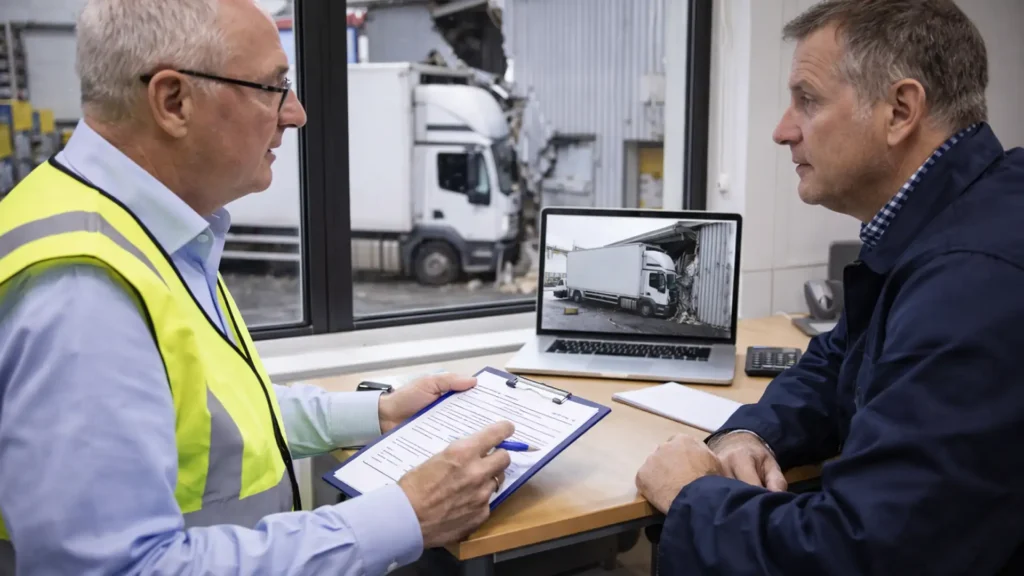
What happens next
A short conversation about the damage and your insurance cover. It’s free, and there’s no obligation.
A qualified loss assessor inspects the property, records the damage and identifies what should form part of the claim.
Documentation, valuations, insurer communication and negotiations are handled for you. You’re kept informed at every stage.
We deal with your insurer on the settlement under the terms of your policy. The insurer pays you directly.
Step 01 is a free, no-obligation conversation.
Public loss assessors
We deal with your insurer for you.
We keep you informed at every stage.
Talk to a loss assessor. The initial consultation is free, with no obligation.
24/7 helpline 01 870 9210